By Raphael Minder in Hong Kong
Published: February 14 2008 02:00 | Last updated: February 14 2008 02:00
A fund management company backed by American International Group is planning to sell a 50 per cent stake in InterGen, a power producer, in a transaction that is likely to fetch between $1bn and $1.5bn, according to people familiar with the situation.
The planned divestment comes almost three years after AIG Highstar Capital and the Ontario Teachers’ Pension Plan jointly acquired InterGen for $1.75bn from Royal Dutch Shell, the Anglo-Dutch oil company, and Bechtel of the US.
InterGen has assets across the world, including power plants in the UK, the Netherlands, Mexico and Australia.
At the time of the 2005 takeover, it had 10 operational power plants with a combined capacity of 5,500 MW. But it has since been expanding its operations, notably in Asia and Europe.
It is adding a €480m ($699m) power plant in the Netherlands and has recently started production at two natural-gas fired power plants in the UK. The $1bn construction of a power station in Singapore has been delayed because of a disputed gas supply contract.
When they acquired InterGen, AIG and the Canadian pension fund also assumed $3.6bn in debt.
However, they have since refinanced the company, selling about $1.9bn in bonds last July.
While InterGen is privately held, a banker familiar with the energy sector estimated that the refinancing, coupled with recent investments, had boosted InterGen’s value to close to $3bn.
The sale by AIG could attract several power companies, as well as Australian and other energy funds. It is also unclear whether Ontario Teachers’ will hold on to its stake.
Neither AIG nor Ontario Teachers would comment on their plans for InterGen.
The divestment comes amid strong interest for power assets, particularly in the Asia-Pacific region, where separate billion-dollar auctions are scheduled to take place this year.
Lehman Brothers is managing the sale.
Additional reporting by Bernard Simon in Toronto
Copyright The Financial Times Limited 2008
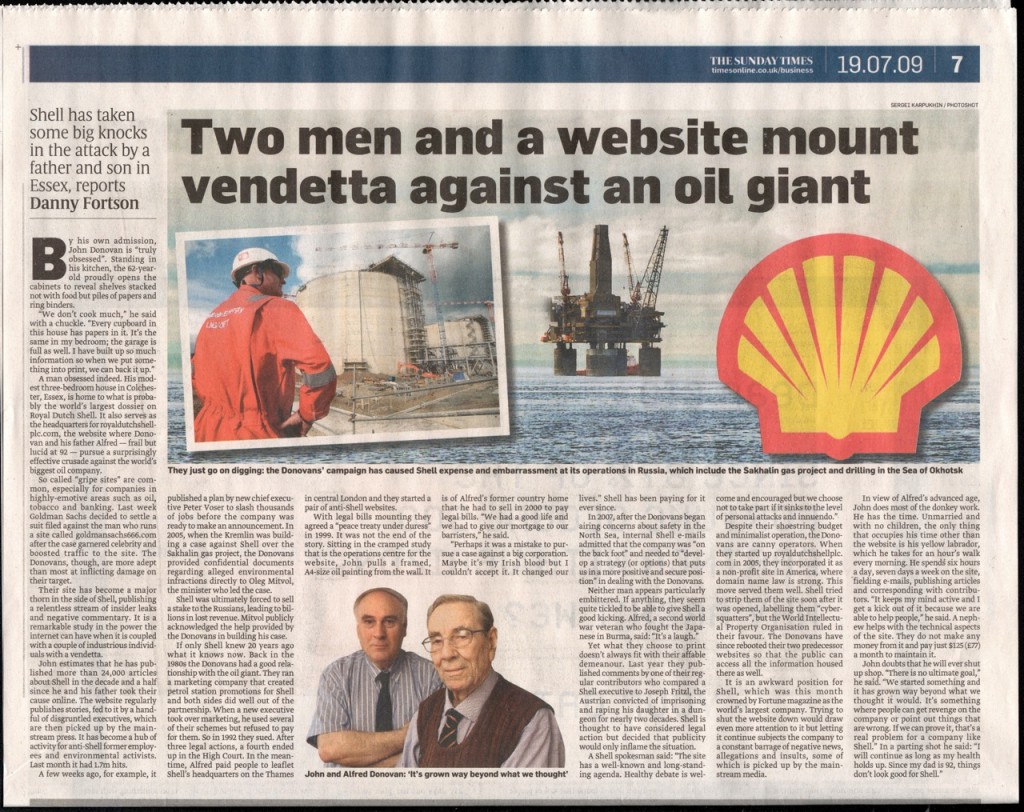
This website and sisters royaldutchshellplc.com, shellnazihistory.com, royaldutchshell.website, johndonovan.website, and shellnews.net, are owned by John Donovan. There is also a Wikipedia segment.


 Royal Dutch Shell conspired directly with Hitler, financed the Nazi Party, was anti-Semitic and sold out its own Dutch Jewish employees to the Nazis. Shell had a close relationship with the Nazis during and after the reign of Sir Henri Deterding, an ardent Nazi, and the founder and decades long leader of the Royal Dutch Shell Group. His burial ceremony, which had all the trappings of a state funeral, was held at his private estate in Mecklenburg, Germany. The spectacle (photographs below) included a funeral procession led by a horse drawn funeral hearse with senior Nazis officials and senior Royal Dutch Shell directors in attendance, Nazi salutes at the graveside, swastika banners on display and wreaths and personal tributes from Adolf Hitler and Reichsmarschall, Hermann Goring. Deterding was an honored associate and supporter of Hitler and a personal friend of Goring.

 Deterding was the guest of Hitler during a four day summit meeting at Berchtesgaden. Sir Henri and Hitler both had ambitions on Russian oil fields. Only an honored personal guest would be rewarded with a private four day meeting at Hitler’s mountain top retreat.


 IN JULY 2007, MR BILL CAMPBELL (ABOVE, A RETIRED GROUP AUDITOR OF SHELL INTERNATIONAL SENT AN EMAIL TO EVERY UK MP AND MEMBER OF THE HOUSE OF LORDS:


 MORE DETAILS:


 A head-cut image of Alfred Donovan (now deceased) appears courtesy of The Wall Street Journal.