THE WALL STREET JOURNAL
JULY 30, 2009 1.35 P.M. ET
By MATTHEW CURTIN
The Royal Dutch Shell conundrum is clear. Heavy investment, falling revenue and high costs are not a good mix for creating shareholder value. New Chief Executive Peter Voser has a long way to go to resolve it despite tough talk on tackling Shell’s inefficiencies.
Shell has one of the industry’s heaviest capital spending programs, with nearly $60 billion planned over this year and next. It is investment that won’t translate into significant growth in oil and gas production before 2011-2012.
But as an 8% decline in output and 70% drop in second-quarter earnings per share show, there may be jam tomorrow, but there’s a lot less today. Shell has above-average exposure to the industry’s worst problems: runaway costs, poor demand for natural gas, weak refining margins and political trouble. In Shell’s case, it’s conflict in the oil-rich Niger Delta. Second-quarter earnings at Spain’s Repsol were down just 62%. BP’s fell 53%.
So to protect Shell’s generous dividend policy — the interim payout is up 5% — Mr. Voser has to continue his assault on the oil group’s cost base, one of the few things he can influence. Having axed 20% of senior management on his promotion, Mr. Voser promises more cuts among Shell’s management.
Shell won’t quantify what further headcount reductions it has in mind or give exact savings targets. All Mr. Voser will say is that there are billions of dollars of potential economies at a company that spends $150 million a day on supplies and contractors. The $3 billion that BP hopes to strip out of its business this year, albeit flattered by foreign-exchange gains, shows what Shell might achieve. It matched BP’s first-half reduction of $2 billion.
If investors remain unimpressed, it is perhaps because they have heard this before. Shell management has touted its “strategic cost leadership” since the 1990s but failed to deliver a permanently leaner business. At a forward earnings multiple of eight times, the stock trades at roughly a 10% discount to its peers. It has missed out on the 13% rally in the European sector this year, falling 9%. Mr. Voser will have to show much more for his restructuring efforts before that discount narrows.
Write to Matthew Curtin at [email protected]
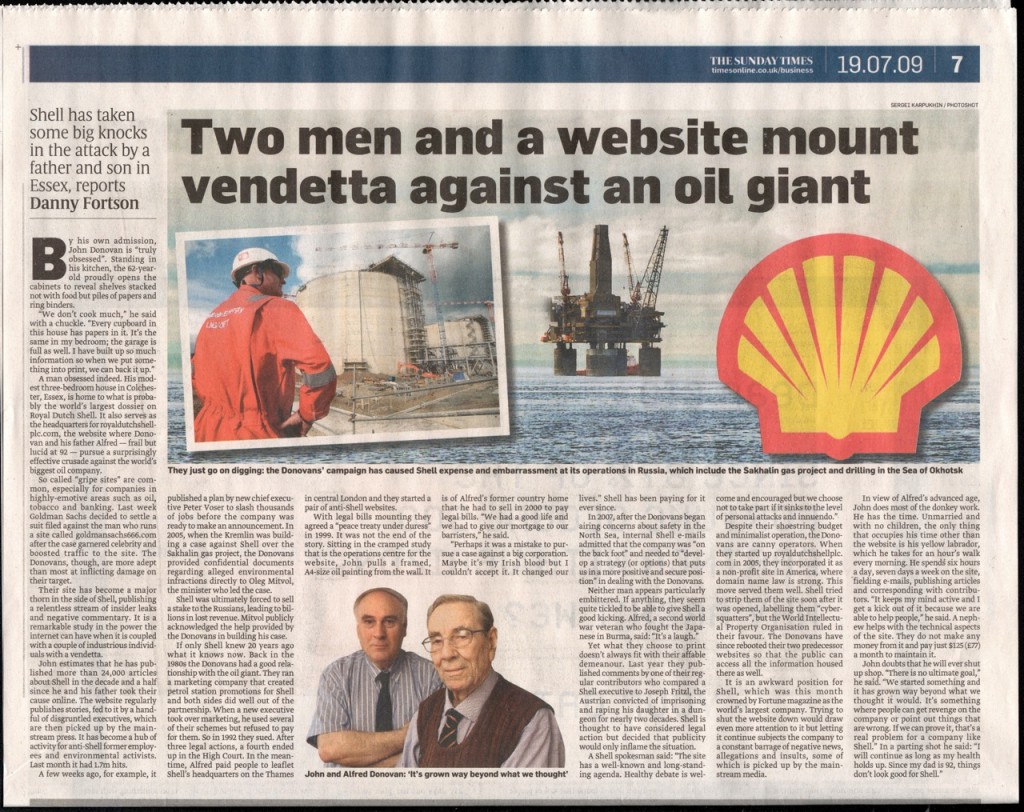
This website and sisters royaldutchshellplc.com, shellnazihistory.com, royaldutchshell.website, johndonovan.website, and shellnews.net, are owned by John Donovan. There is also a Wikipedia segment.


 Royal Dutch Shell conspired directly with Hitler, financed the Nazi Party, was anti-Semitic and sold out its own Dutch Jewish employees to the Nazis. Shell had a close relationship with the Nazis during and after the reign of Sir Henri Deterding, an ardent Nazi, and the founder and decades long leader of the Royal Dutch Shell Group. His burial ceremony, which had all the trappings of a state funeral, was held at his private estate in Mecklenburg, Germany. The spectacle (photographs below) included a funeral procession led by a horse drawn funeral hearse with senior Nazis officials and senior Royal Dutch Shell directors in attendance, Nazi salutes at the graveside, swastika banners on display and wreaths and personal tributes from Adolf Hitler and Reichsmarschall, Hermann Goring. Deterding was an honored associate and supporter of Hitler and a personal friend of Goring.

 Deterding was the guest of Hitler during a four day summit meeting at Berchtesgaden. Sir Henri and Hitler both had ambitions on Russian oil fields. Only an honored personal guest would be rewarded with a private four day meeting at Hitler’s mountain top retreat.


 IN JULY 2007, MR BILL CAMPBELL (ABOVE, A RETIRED GROUP AUDITOR OF SHELL INTERNATIONAL SENT AN EMAIL TO EVERY UK MP AND MEMBER OF THE HOUSE OF LORDS:


 MORE DETAILS:


 A head-cut image of Alfred Donovan (now deceased) appears courtesy of The Wall Street Journal.