Published: November 7 2007 09:26 | Last updated: November 7 2007 11:16
In recent years, Europe’s two biggest oil companies by market capitalisation have embodied different bets on the oil price. With a much smaller refining base than its supermajor peers, and shunning costly, unconventional fuel sources like oil sands, BP has been counting on prices falling. Lord Browne, chief executive until this summer, was banking on $40 a barrel in the medium term, slackening to $25 or $30 further out. Shell, meanwhile, implicitly believes in prices being stronger for longer. Since late 2004 it has gone out on a limb, developing big, long-life upstream projects, complemented by a solid downstream business able to process complex fuels.
The stock market, however, continues to reward conservatism, leading to a valuation gap. As Shell has ploughed more cash back into its business – capital expenditure consumed over 70 per cent of post-tax cash flow from operations last year, compared to 54 per cent at BP – its valuation has consistently lagged its rival by around 10 per cent in terms of debt-adjusted cash flow multiples, and about five per cent on earnings multiples.
The trade-off between short term cash flow generation and production growth is a challenge for BP’s new chief executive Tony Hayward. He has yet to outline his view on oil prices or capex, but there are some hints that he could unpick the strategy of his predecessor. A recent stray aside from the company’s EMEA chief suggested BP was eyeing a return to Qatar, which sits on the world’s third-largest gas reserves, after a 15-year hiatus. Speculation is now mounting that Mr Hayward may look for a way back into Canadian oil sands – a business BP twice exited under Lord Browne, blaming insufficient returns.
If deals and capital spending follow, it would represent a U-turn by BP. It is also understandable why oil majors use cautious long term forecasts. Nonetheless with spot oil prices now almost four times BP’s current planning assumption, it looks likely that Mr Hayward will turn the capex tap on.
Copyright The Financial Times Limited 2007
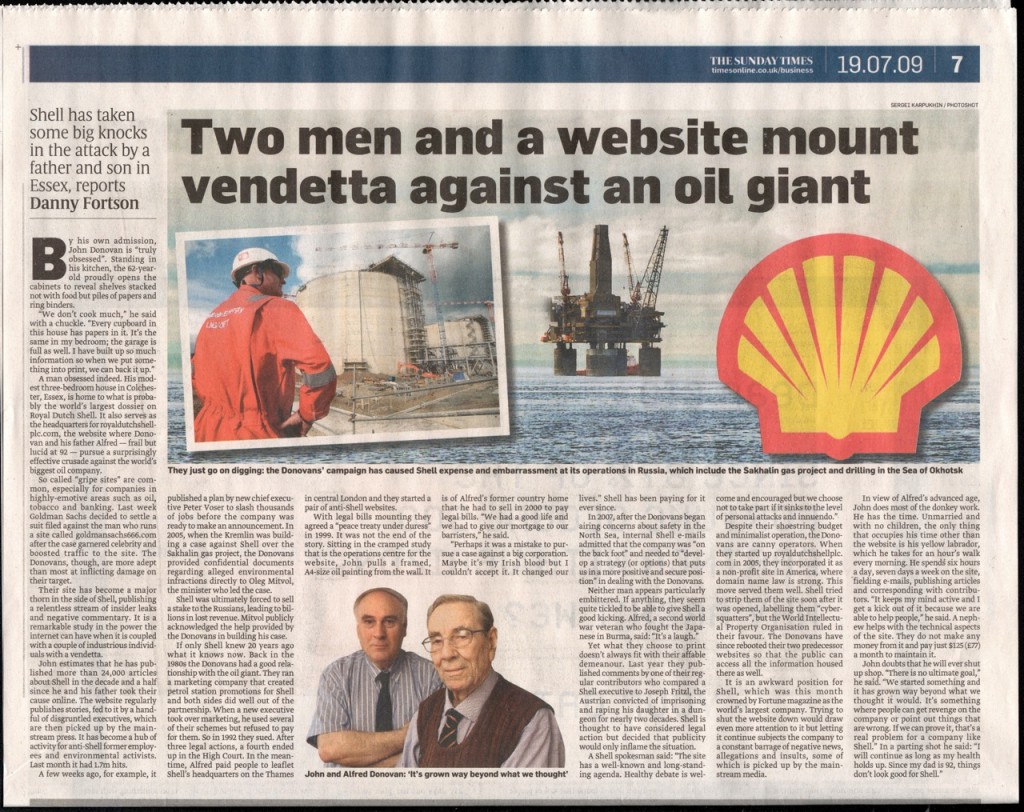
This website and sisters royaldutchshellplc.com, shellnazihistory.com, royaldutchshell.website, johndonovan.website, and shellnews.net, are owned by John Donovan. There is also a Wikipedia segment.


 Royal Dutch Shell conspired directly with Hitler, financed the Nazi Party, was anti-Semitic and sold out its own Dutch Jewish employees to the Nazis. Shell had a close relationship with the Nazis during and after the reign of Sir Henri Deterding, an ardent Nazi, and the founder and decades long leader of the Royal Dutch Shell Group. His burial ceremony, which had all the trappings of a state funeral, was held at his private estate in Mecklenburg, Germany. The spectacle (photographs below) included a funeral procession led by a horse drawn funeral hearse with senior Nazis officials and senior Royal Dutch Shell directors in attendance, Nazi salutes at the graveside, swastika banners on display and wreaths and personal tributes from Adolf Hitler and Reichsmarschall, Hermann Goring. Deterding was an honored associate and supporter of Hitler and a personal friend of Goring.

 Deterding was the guest of Hitler during a four day summit meeting at Berchtesgaden. Sir Henri and Hitler both had ambitions on Russian oil fields. Only an honored personal guest would be rewarded with a private four day meeting at Hitler’s mountain top retreat.


 IN JULY 2007, MR BILL CAMPBELL (ABOVE, A RETIRED GROUP AUDITOR OF SHELL INTERNATIONAL SENT AN EMAIL TO EVERY UK MP AND MEMBER OF THE HOUSE OF LORDS:


 MORE DETAILS:


 A head-cut image of Alfred Donovan (now deceased) appears courtesy of The Wall Street Journal.